

Hello Gobbledeers,
How’s it going?
Welcome to Gobbledy issue 150! Lordy that’s a lot. Thanks for continuing to read this as we approach year 3.
Today - a wee, slight, miniscule bit of a departure…I wanted to talk a little more broadly about strategy. I found an article from 45 years ago that’s incredibly applicable today and I thought I’d share some thoughts about it. But also there’s some nonsense, as usual…
Maybe don’t make a funny video to promote your product if you’re not funny.
A 1978 Harvard Business Review article offers helpful advice for struggling tech companies (even if the article was talking about adding machines…)
Finally, a Great Use for AI
One of the difficult things about a startup is that you really have to work hard to catch people’s attention. When you’re just getting started, it’s hard to get people to notice you.
If you’re in a really crowded space - say, any sort of AI-based tooling - it’s even more challenging. There’s so much noise - how do you cut through it and get people to remember you?
Well, one tried-and-true method is to create a video that grabs people’s attention. The granddaddy of this approach is from Dollar Shave Club, which kicked off their business 12 years ago with a truly great piece of marketing:
It was so great that if you worked in marketing for a company (literally, any company) 12 years ago, somebody came up to you and said, “You know what we should do? One of those funny videos like Dollar Shave Club.”1 To paraphrase Dollar Shave Club, “Great f’ing idea!”
Which is why if you’re not an actually funny person with an actually funny idea for a launch video, you should very definitely NOT try to make a funny video.
Like, for example, maybe you are a couple of Duke students who have created an AI-based tool called Optifye that will monitor your factory workers’ performance and alert the boss when someone is slacking off. And maybe you’re part of fancypants Internet incubator Y Combinator. And maybe you make this incredible* video:
(*I don’t mean incredibly good)

So you make this “funny” video, where you show how you can monitor the output of every worker on your factory floor, then you find one worker - whom you call “Number 17” isn’t hitting his numbers.
Boss: “Hey number 17, what’s going on man? You are in red”
Worker number 17: “I have been working all day.”
Boss: “Working all day? You haven’t hit your hourly output even once today. And you have 11.4% efficiency, this is really bad!”
Worker number 17: “It’s just been a rough day.”
Boss: “Rough day? More like a rough month.”
Hilarious!
Y Combinator posted this, congratulating the Optifye team on their launch:
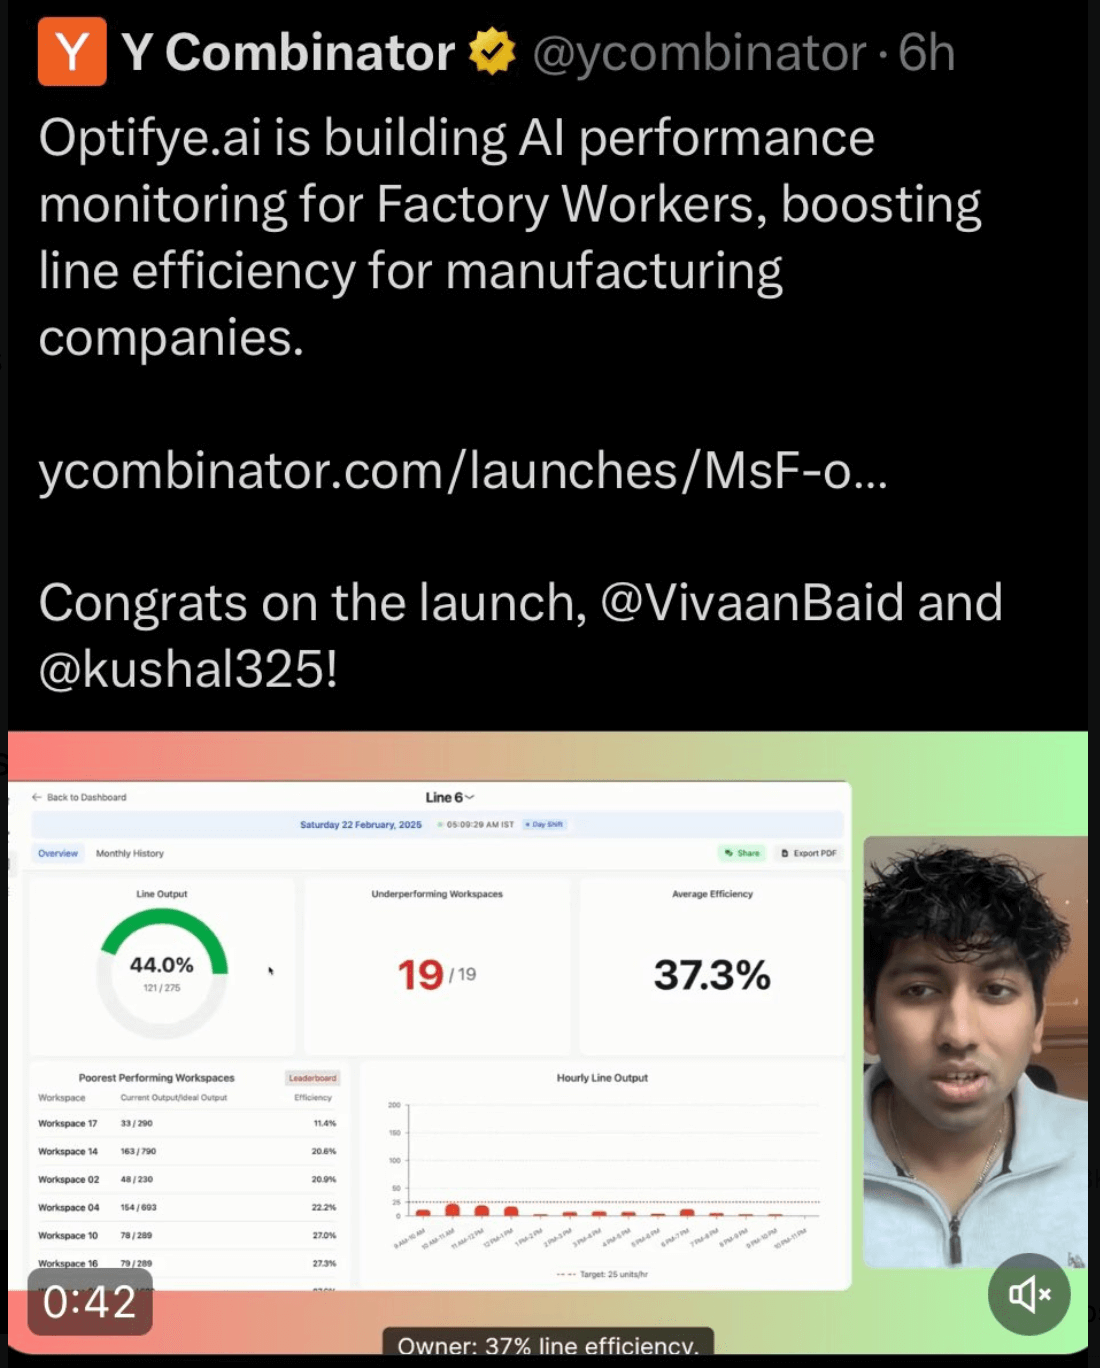
Annnnnnnnnnd then after some online backlash, they took back their congratulations and deleted the post. Take that!
What I’m saying is this: if you create a product that’s meant to improve efficiency - even if “improve efficiency” means you have to fire some people - maybe you don’t actually say it’ll fire people.**
(**Unless you’re Elon Musk.)
(Thanks 404 Media for the background on the story.)
Thriving as a Low Market Share Player…
Wanna go on a little trip? A little trip in the Gobbledy Time Machine (tm)?
That was rhetorical - we’re going on the goddamned trip in the time machine, whether you like it or not.
So something I’ve noticed about tech companies is that they tend to believe that tech businesses are completely different from businesses in other industries.
Or rather, that the typical strategies of those non-tech businesses do not apply to them.
We first saw this during the Web 1.0 days when every tech company said that profits don’t matter, and that as long as you grow - profits aside - you will be successful. Amazon spent many, many quarters telling Wall Street analysts that it’s OK they were losing money because they were investing in growing the business, and once the business reached scale, they would have such an operational advantage that nobody could compete with them, and they would be profitable.
That’s almost exactly what happened.*
(*Almost. Their core eCommerce business is barely profitable, but their AWS and advertising units are wildly profitable.)
In the 2.0 days (let’s call it 2010-2021), tech companies believed (correctly, it turns out) that we lived in a winner-take-all world, and if you grew fast enough (which was only possible because interest rates were basically zero, so capital was easily available), you could - it turns out - get scale without being profitable and still have what was considered a successful business (hi, Uber).
If you work for a tech company today (unless you work for an AI company - which maybe you do, I don’t know!, you do not have easy access to capital, so you cannot grow at all costs. That’s a bummer.
The other bummer is that you may be run by a person (and/or people and/or a board) who has/have never known anything EXCEPT grow-at-all-costs. The harsh reality is that the people running the company that you work for many not have ever had to run a company in the environment they’re in.
Which is why we busted out the time machine.
If there was a Gobbledy Book Club (tm), I would have us all read this seminal (heh heh, seminal) 1978 article from the Harvard Business Review titled “Strategies for Low Market Share Businesses.”
I know, snoozer! Amirite?
Why are we talking about that article? Because many, many (many!) tech companies are no longer the high-growth businesses they thought (or hoped) they’d be, and are instead actually low market share businesses, where they compete in a market where there’s a clear winner or two (maybe an oligopoly, like Salesforce and Hubspot in CRM) but there are a bunch of low market share competitors trailing them.
What’s helpful about the article is that the authors don’t dismiss these companies, and in their research they find that these smaller market share businesses can be profitable and successful, and they share four reasons for their success.
And I found those four reasons to be remarkably applicable to many of today’s tech companies:
“They carefully segment their markets.”
“They use research and development funds efficiently.”
“They think small.”
“Their chief executives’ influence is pervasive.”
Let’s dig into these a tiny bit…
Segment their markets
The authors suggest that successful low market share companies define their markets “in unique and creative ways” - segmenting, for example, by the level of service they offer, distribution channel, price-to-value ratio, etc.
But, most importantly, they must compete only in segments where their “strengths will be most highly valued and where its large competitors will be most unlikely to compete.” In other words, find a target market where your competition will let you win, but doing that will require re-thinking how you segment the marketplace.
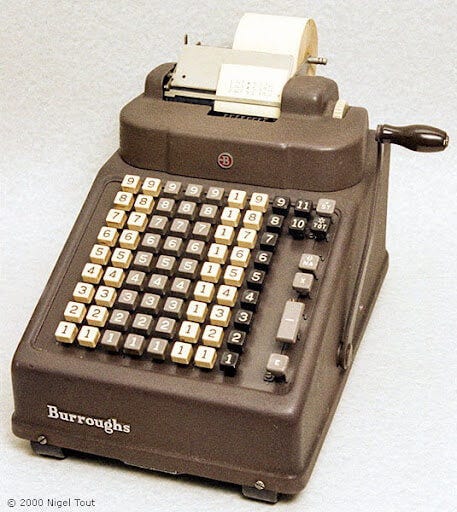
As an example, the authors talk about long-defunct computer manufacturer Burroughs, which competed with market leader IBM by focusing entirely on the financial market, because it had deep roots in the (I’m not making this up) adding machine market.
Use R&D funds efficiently
Rather than spreading investment around on different products, successful small market share companies focus their investment dollars where competitors lag significantly. Again, this means focusing investment and letting go of markets and products where you cannot compete. I admit that this is difficult.
But in the article they quote an executive with Crown Cork and Seal (a company still around today as Crown Holdings) who says, “We are not truly pioneers…however, we do have tremendous skills in die forming and metal fabrication, and we can move to adapt to the customer’s needs faster than anyone else in the industry.”
They focused their investments in that area because they have expertise there (that others cannot touch), and it ties to a clear value proposition - it allows them to adapt to customer needs faster than anyone else.
Letting go of markets that you’re in can feel like a demoralizing retreat, but if assets are re-allocated into areas where you can leverage unique knowledge, it can create a competitive advantage that the market leader cannot touch.
Think small
The idea is that successful low market share companies are “content to remain small…and emphasize profits rather than sales growth or market share, and specialization rather than diversification.”
Because many tech companies take venture funding, it’s difficult to remain small and keep your investors happy.
But there are a giant pile of tech companies who find themselves with low market share and also low growth. That’s a mess.
To paraphrase comedian Nate (“books are the key to smart”) Bargatze, “small is the key to big.” For companies struggling with low market share, they may be better off shrinking their business and specializing, with the idea that if they can get enough of a smaller market, they’ll be able to re-start their growth from a healthier base.
They again give the example of Crown Cork, which had 50% of the oil can market (?) and decided to get out of it because they felt that new technologies in that market limited their long-term growth and they could get a higher return on capital by re-deploying those assets elsewhere in the company.
In a time when it is challenging-to-impossible to raise more funding (if you’re not an AI company), tech companies may need to think more like a manufacturer, and shrink when necessary to ensure that they are deploying their limited assets to a way that allows them to compete profitably in their market.
The CEO Is Highly Influential
You may remember the recent kerfuffle about “founder mode” - the idea that tech founders need to be micromanagers - as Paul Graham put it, “There are things founders can do that managers can't, and not doing them feels wrong to founders, because it is.”
This - like so many ideas - is not a new idea. The authors of this article say that the final characteristic of successful small market share companies is that their CEO is, as we would say today, in “founder mode.” As they put it, these CEOs “have all been described as extremely strong-willed individuals who are involved in almost all aspects of company operations.”
I will be the first to say that I find it difficult (to say the least) to work for this type of founder. However, when it comes to being a successful small market share company, it does not matter what I think (gasp!).
To be profitable when you only have single digit market share, your CEO needs to be hands-on. Much to your chagrin, probably…
Thanks for letting me chat a little strategy here - I know that for many of you working for companies that seem to be stagnating, it can feel like you’re the only company in that situation, and that the situation has never happened before. Hardly. Share that framework with your boss - assuming they’re willing to listen, it’s a good starting point for a conversation about how to re-focus the company when you’re not the leader in the market.
Jazz Band
OK, today was a little heavier than usual - sometimes ya gotta take a little medicine with the sugar or something something something. So let’s finish on a note that has nothing at all to do with marketing, but it’s my newsletter (for you! everything is for you!) and here we go:
Were you in jazz band in high school? When you read the phrase “high school jazz band” what pops into your head? Is it, “Oh yes, the guy I wanted to take me to the prom in high school was in jazz band, and that’s how I knew he was amazing?” Hm.
I was in jazz band. And I know how people felt about us jazz band types, and I’ve definitely come to terms with that and now that I’m an adult, I realize that those stereotypes don’t really reflect on me inasmuch as they reflect on my wife (Gobbledy reader Susan B., mother of Gobbledy reader Scarlett B.) who chose to marry a guy who was in jazz band. So who’s the sad high school loser now?
(Deep breath)
Oh yes, jazz band.
I’m not sure any of us in jazz band actually knew what a jazz band was supposed to sound like (which is why we didn’t much sound like one).
But now I know…
I recently came across this clip of drummer-and-owner-of-the-worlds-worst-hairpiece Buddy Rich performing on Johnny Carson’s show back in 1974. I had no idea this is what we were supposed to be reaching for. As a friend of mine said, “they look like an accounting firm decided to start a band.” True. But also, they’re absolutely incredible, and Rich mentions at the end that the band had just gotten the extremely complex music that day and you can see from his jubilation at the end when he high-fives the band, that he - arguably the greatest drummer in the world - is amazed by how good these guys are.
Enjoy…
As always, thanks for reading to the end (it’s the best part). If you want to chat about marketing challenges you’re having, or how you were in high school jazz band but people went to the prom with you anyway, here’s my Calendly link - I really enjoy chatting with readers.
Also, telling people about this newsletter is easy:
Yes, of course this happened to me.
To clarify - I did marry you but might not have gone to the prom with you (as if!)!
Thanks for the Buddy Rich video. Funny story you may appreciate about Buddy Rich: Bill Graham, legendary rock producer, was a big jazz fan. There was a time during the 70's when rock bands like Led Zeppelin, Ten Years After, etc were playing 15-20 minute drum solos in their shows. Graham thought this was horrible because these drum solos were awful so he booked Buddy Rich to open a few Rock shows. I know one of them was Ten Years After in SF since I heard an interview with Graham about this. Well Buddy Rich opens the show and does his thing on the drums. Ten Years After saw his performance on the drums and decided to scrap their drum solo on the spot. Nobody could follow that act on the drums. And that was end of long drum solos in Rock & Roll.